By David Parks · eXp Realty · The Apollo Group · 2 min read
Home equity is the difference between your home’s market value and what you owe on your mortgage. It grows as you pay down your loan and as the home’s value changes.
If your home is worth $500,000 and you owe $350,000, your equity is $150,000. This is a simple illustration, and your numbers will differ.
| Key point | What it means |
|---|---|
| Paying down principal | Each payment reduces what you owe. |
| Appreciation | If market prices rise, your equity rises too. |
| Improvements | Some upgrades can add value, though not always dollar for dollar. |
| Down payment | A larger down payment starts you with more equity. |
Homeowners can use equity through a home equity loan or line of credit, a cash-out refinance, or by selling and putting proceeds toward the next home. Each option has costs and risks.
Values can go down as well as up, and borrowing against equity reduces your cushion. A lender and financial advisor can help you decide what makes sense. A free home valuation can give you a sense of where your equity stands.
This article is general information, not legal, tax, financial or inspection advice. Every home and situation is different, so confirm details with a licensed inspector, lender, attorney or tax professional.
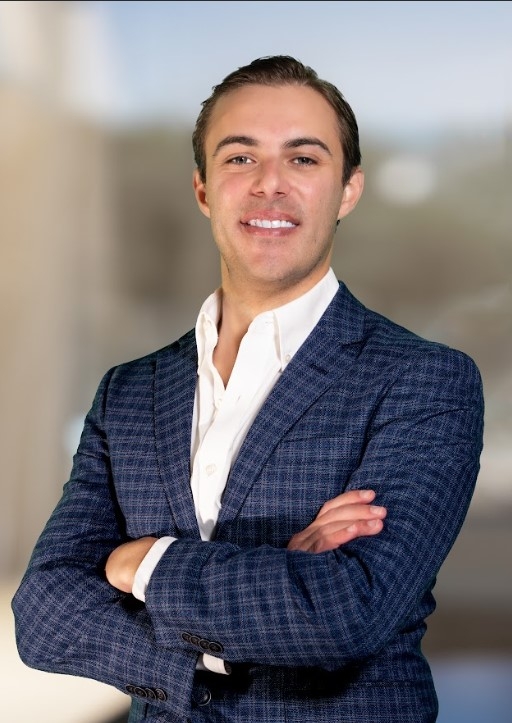
David is a Greater Denver real estate advisor with eXp Realty and The Apollo Group (Colorado broker license FA100103211). He has closed more than $55 million in volume, earned eXp Icon status in 2025, and holds a 5.0 rating on Zillow from 27 verified reviews.
Denver market updates, new listings, and local tips — no spam, unsubscribe anytime.